
Lease Accounting Journal Entries with Worked Examples
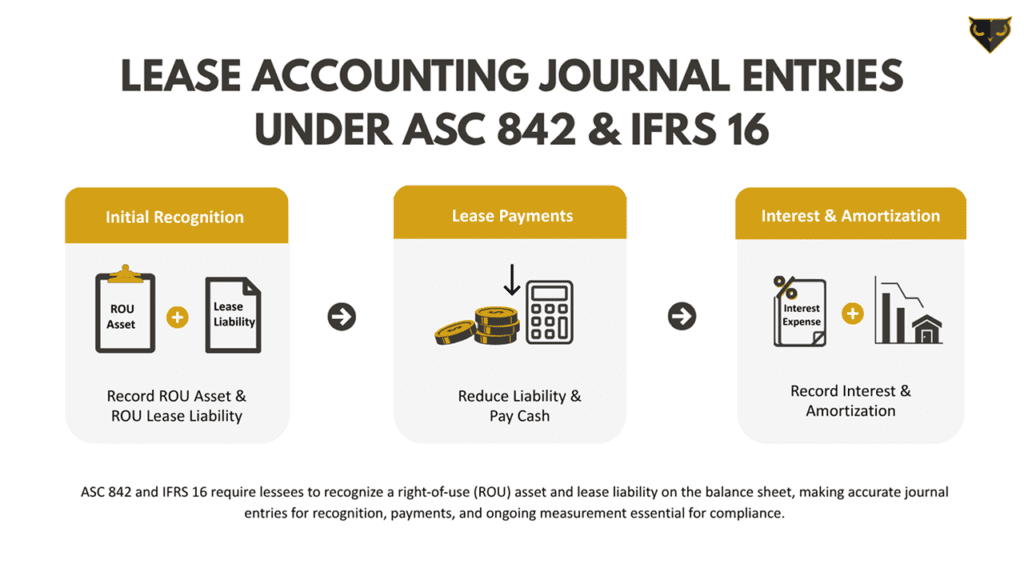
What Are Lease Accounting Journal Entries?
A lease accounting journal entry is the bookkeeping record that captures every accounting consequence of a lease: at lease commencement, every reporting period through the end of the term, and at any modification, reassessment, or termination event in between.
Where one rent-expense entry used to suffice, lessees now need an initial recognition entry, an interest entry, an amortization entry, a payment entry, and frequently remeasurement entries, each with rules that differ between ASC 842 and IFRS 16. This guide walks through every one, with worked examples you can reproduce and the Day 2 events that trip up spreadsheet teams.
Initial Recognition: Recording the ROU Asset and Lease Liability
At lease commencement (the date the lessor makes the asset available for use), the lessee recognizes a right-of-use asset and a corresponding lease liability. Both are measured at the present value of future lease payments, discounted at the rate implicit in the lease or, when that rate is not readily determinable, the lessee's incremental borrowing rate (IBR). The ROU asset is then adjusted for prepaid rent, initial direct costs, and any lease incentives received.
The worked example used throughout this guide
Imagine your company signs a 5-year office lease: $100,000 payable at the end of each year, 5% IBR, and no prepaid rent, initial direct costs, or lease incentives. The present value of five annual payments of $100,000 discounted at 5% is $432,948, the value at which both the ROU asset and the lease liability are initially recorded. This is an operating lease under ASC 842 and a capitalized lease under IFRS 16.
The initial entry (identical for ASC 842 operating, ASC 842 finance, and IFRS 16)
Under ASC 842, an operating lease still requires balance sheet recognition, and the initial entry is identical for operating and finance leases. IFRS 16 eliminates the operating-lease classification almost entirely but recognizes every capitalized lease the same way. So all three scenarios share one initial entry:
| Account | Debit | Credit |
|---|---|---|
| Right-of-Use Asset | $432,948 | |
| Lease Liability | $432,948 |
To record the ROU asset and lease liability at lease commencement (5-year office lease, $100,000 annual payment, 5% IBR). Initial recognition is identical across all three scenarios. Classification only changes how you record subsequent entries: interest, amortization, and income-statement presentation.
How to Determine Lease Classification Under ASC 842
Before you can record the right entries, you need to know what type of lease you have. Under ASC 842 a lessee runs a five-criteria test at commencement. If any one applies, it's a finance lease:
- Ownership transfers to the lessee by the end of the lease term
- The lessee has a purchase option and is reasonably certain to exercise it
- The lease term covers the major part of the asset's remaining economic life (generally 75% or more in practice)
- The present value of lease payments is substantially all of the fair value of the asset (generally 90% or more in practice)
- The asset is so specialized it has no alternative use to the lessor at the end of the term
If none of the five apply, it's an operating lease. This decision is made once, at commencement, and drives the entire subsequent entry pattern, which is why documenting it matters. Auditors will ask.
Year 1 Entries: Interest, Amortization and Payment
Beginning liability $432,948 × 5% = $21,647 interest; $100,000 payment − $21,647 = $78,353 principal; ending liability $354,595. Although this example uses annual payments for clarity, real-world leases usually pay monthly. The same components apply, computed at a monthly periodic rate.
ASC 842: Operating Lease (Year 1 entries)
The income statement shows a single, straight-line lease expense. Total lease cost across five years is $500,000, so the straight-line annual expense is $100,000. ROU amortization is plug-balanced: straight-line expense minus interest ($100,000 − $21,647 = $78,353).
| Account | Debit | Credit |
|---|---|---|
| Lease Expense | $100,000 | |
| Cash | $100,000 | |
| Lease Liability | $78,353 | |
| Right-of-Use Asset (amortization) | $78,353 |
To record straight-line lease expense, the cash payment, and the corresponding reductions in the lease liability and ROU asset for Year 1 (operating lease, ASC 842).
ASC 842: Finance Lease (Year 1 entries)
Expense splits into two distinct lines. Interest follows the effective-interest method ($21,647). Amortization is straight-line over the shorter of the lease term or useful life ($432,948 ÷ 5 = $86,590).
| Account | Debit | Credit |
|---|---|---|
| Interest Expense | $21,647 | |
| Lease Liability | $78,353 | |
| Cash | $100,000 |
To record interest expense, principal reduction, and the cash payment for Year 1 (finance lease, ASC 842).
| Account | Debit | Credit |
|---|---|---|
| Amortization Expense (ROU Asset) | $86,590 | |
| Accumulated Amortization (ROU Asset) | $86,590 |
To record straight-line amortization of the ROU asset for Year 1. Note the front-loaded pattern: total Year 1 expense is $108,237 vs a flat $100,000 under operating treatment. As the liability shrinks, interest declines and total expense falls below $100,000 in later years.
IFRS 16: Year 1 entries (single model)
Under IFRS 16, the entries are identical to the ASC 842 finance lease above: interest plus amortization, with no straight-line, plug-balanced operating alternative.
ASC 842 vs IFRS 16: Journal Entry Differences
| Topic | ASC 842 Operating | ASC 842 Finance | IFRS 16 |
|---|---|---|---|
| Initial recognition | ROU + Liability | ROU + Liability | ROU + Liability |
| Income statement | Single lease expense | Interest + Amortization | Interest + Amortization |
| ROU amortization | Plug-balanced | Straight-line | Straight-line |
| EBITDA impact* | Lower EBITDA | Higher EBITDA | Higher EBITDA |
| Index/CPI payment changes | Expensed as incurred | Expensed as incurred | Liability remeasured |
| Low-value exemption | Not available | Not available | Available |
| Short-term exemption | Available (≤12 mo) | Available (≤12 mo) | Available (≤12 mo) |
*Under an operating lease, the single lease expense sits above EBITDA and reduces it. Under ASC 842 finance lease and IFRS 16 treatment, interest and amortization sit below EBITDA, so EBITDA is higher for the same lease. This is a presentation difference, not an economic one.
Everything above is the easy version.
One lease. One period. No surprises. That's the version that fits in a blog post. Your portfolio isn't that. It's mid-term modifications, index resets, partial terminations, impairments, FX, and a close deadline that doesn't move. Every one is another manual journal entry, and the one you miss is the one the auditor finds.
Black Owl's goal is simple: you never write another manual journal entry.
Every entry, every Day 2 event, ASC 842 and IFRS 16, calculated, posted to your ERP (NetSuite, SAP, JD Edwards, QuickBooks), and backed by a full audit trail. Automatically.
See it run on your actual leases: book a 10-minute demo →Day 2 Events: Where Manual Entries Break Down
Initial recognition is the part everyone gets right. The complexity, and the audit risk, lives in what happens next. Each event below needs its own journal entry, and these are the entries spreadsheets routinely miss.
Lease modifications and remeasurement
A term extension, scope change, or payment change that isn't accounted for as a separate contract requires re-discounting the remaining payments at a discount rate updated as of the modification date, adjusting the lease liability, and booking the difference to the ROU asset. Miss it and the books carry a stale liability.
| Account | Debit | Credit |
|---|---|---|
| Right-of-Use Asset | $X | |
| Lease Liability | $X |
Increase in liability from a modification, with the offset capitalized to the ROU asset (decreases reverse the signs).
CPI and index rent resets
This is one of the sharpest differences between the two standards. Under IFRS 16, a change in payments driven by an index or rate remeasures the lease liability using the revised payments and, in most cases, the original discount rate, with the adjustment booked to the ROU asset. Under ASC 842, the index is locked in at commencement and later increases are treated as variable lease payments, expensed in the period incurred. The liability is only updated for the new index level when it's remeasured for some other reason, such as a modification or a change in lease term. Teams reporting under both standards need two different treatments for the same rent increase.
Partial terminations and abandonment
Reducing leased space derecognizes a proportionate share of the ROU asset and lease liability, with any difference booked as a gain or loss, and is one of the most commonly mis-booked events in spreadsheets. Abandonment works differently under ASC 842: the ROU asset isn't derecognized up front, but its amortization is accelerated so it's fully expensed by the date you stop using the space.
Impairment, subleases and FX
ROU assets are subject to impairment testing. When you sublease space, you keep lessee accounting on the head lease and apply lessor accounting to the sublease, so one property now runs two sets of entries. Foreign-currency leases remeasure the lease liability at each reporting date, with FX gains and losses to the income statement. Each is a distinct journal entry, every period.
Common Mistakes in Lease Journal Entries
- Recording the full payment as expense. Under ASC 842 finance leases and IFRS 16, the payment must split into interest and principal.
- Inconsistent IBR application. Different rates across leases or periods create a comparability problem auditors flag.
- Missing modifications and remeasurements. The single most common spreadsheet failure.
- Confusing operating vs finance classification. Misclassification flips the income-statement presentation and EBITDA.
How Software Automates These Entries
Calculating these manually for ten leases is tedious. For a hundred, with monthly entries, quarterly remeasurements, and an audit cycle on top, it's functionally impossible without errors. Black Owl handles the calculation, the entries, and the ERP posting automatically:
- Calculates ROU asset, liability, interest, and amortization at every period end.
- Generates compliant entries for ASC 842 and IFRS 16 and posts them to your ERP.
- Maintains a complete audit trail with every assumption documented (IBR, classification, modifications).
- Handles modifications, remeasurements, and terminations without spreadsheet acrobatics.
- Produces audit-ready reports and roll-forward schedules in one click.
Frequently Asked Questions
What is the journal entry for an operating lease under ASC 842?
At commencement, debit ROU Asset and credit Lease Liability for the present value of future payments. Each period, debit Lease Expense (straight-line) and credit Cash, then plug-balance the ROU Asset and Lease Liability.
How are finance lease journal entries different from operating lease entries?
Finance leases split expense into Interest and Amortization, recorded separately. Operating leases recognize a single straight-line Lease Expense, though the ROU asset and liability still sit on the balance sheet.
Are lease accounting journal entries the same under IFRS 16 and ASC 842?
Initial recognition is the same. Subsequent entries differ: IFRS 16 treats almost every lease like an ASC 842 finance lease, with no straight-line single-expense option.
Can lease accounting software generate journal entries automatically?
Yes. Black Owl generates all required entries from the lease data, posts them to your ERP, and maintains a full audit trail with every assumption documented, the support auditors expect to see during fieldwork.
Stop keeping the schedule alive by hand.
Lease accounting turned a one-line rent expense into a portfolio of entries, schedules, and disclosures that get more complex with every modification. The math is straightforward; the discipline of doing it right, every period, across the whole portfolio, is where teams lose hours and risk findings.
Black Owl does the journal entries for 5 to 5,000 leases so your team never touches one again. The demo is 10 minutes, on your real data.
Show me →Related Resources

Greg Kautz
Greg Kautz, CPA, CMA is a seasoned management consultant and professional accountant with over 40 years of experience in the consulting and energy sectors. At Black Owl Systems, Greg brings deep expertise in ERP systems, corporate finance, strategic planning, and technology integration.
