“Reasonably Certain” Under ASC 842: How to Determine the Lease Term
What reasonably certain means under ASC 842, the economic incentive factors that decide it, how to document the judgment, and three leases scored end to end.

What reasonably certain means under ASC 842, the economic incentive factors that decide it, how to document the judgment, and three leases scored end to end.
Accounting for leasehold improvements and tenant improvement allowances under ASC 842: who paid, how the allowance changes the ROU asset, and the amortization period.
Which variable lease payments enter the lease liability under ASC 842 and IFRS 16, which stay out, and what a CPI increase does to each. With worked figures.
How right-of-use asset impairment works under ASC 842 and ASC 360: triggers, asset groups, the recoverability test, journal entries, and the revised schedule.
The lease commencement date under ASC 842, and how it differs from inception, execution, effective, rent commencement and possession dates. With a worked example.
How to identify embedded leases under ASC 842: the two tests, where they hide, a portfolio search method, and a worked example with journal entries.
Lease abstraction for ASC 842 compared three ways: in-house review, outsourced work, and automated extraction. Which fields extract reliably and which need a human.

Lessee vs Lessor: Key Differences in Roles and Lease Accounting The lessor owns an asset and
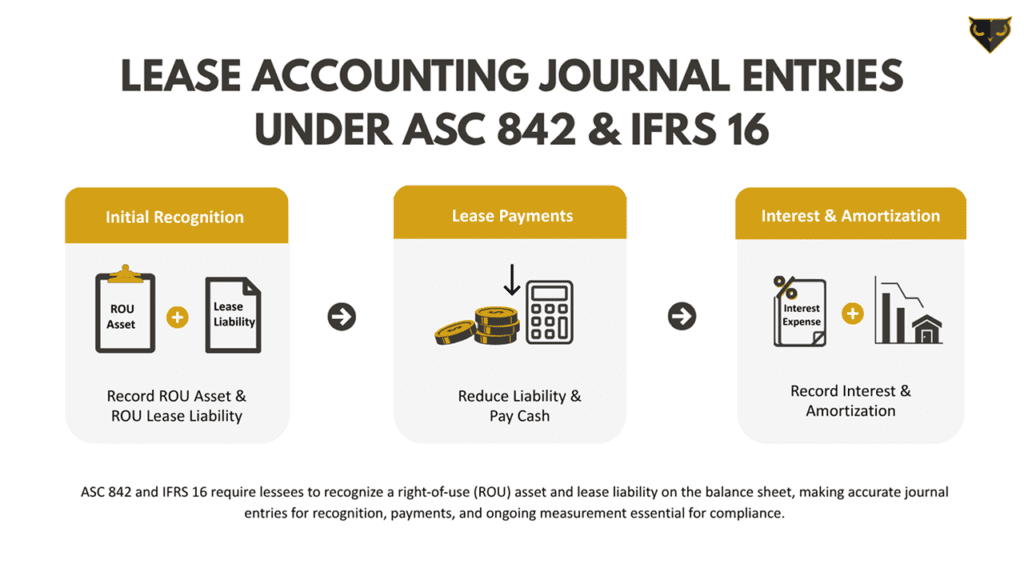
On this page What are lease journal entries? Initial recognition Classification test Year 1 entries ASC

How Does ASC 842 Affect EBITDA? The adoption of ASC 842, the lease accounting standard issued
The Ultimate Guide to ASC 842 Sale-Leasebacks for Finance Teams Selling an asset and immediately leasing

Fixed assets and leased assets both appear on the balance sheet, both support a business’s day-to-day
