
Finance Lease vs Operating Lease: ASC 842 Classification
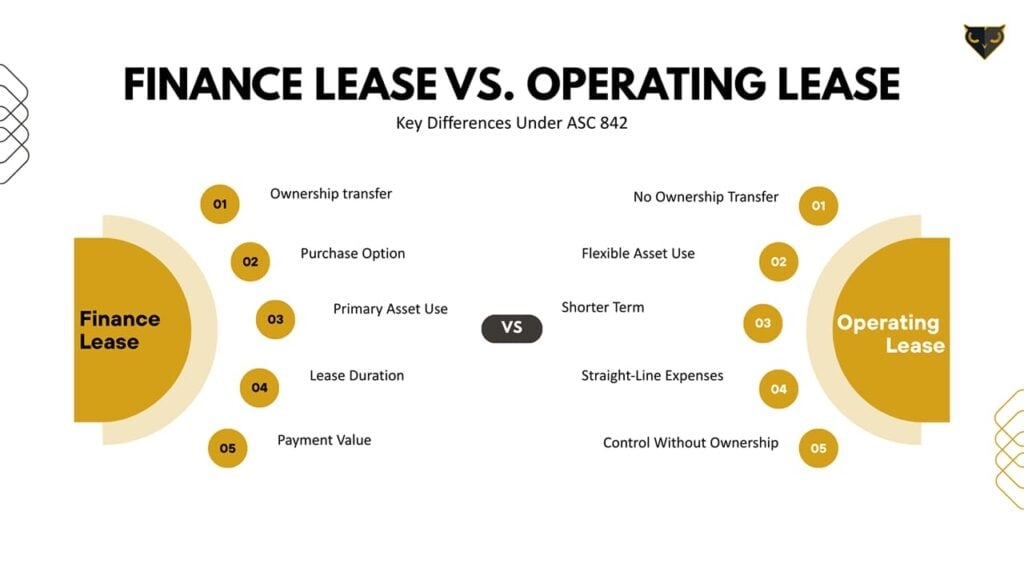
For a finance lease, the lessee records interest and ROU amortization as separate expenses. For an operating lease, the lessee usually records one expense evenly across the lease term. Both usually require a right-of-use asset and lease liability on the lessee’s balance sheet. ASC 842 uses five tests to decide which lease type applies.
Black Owl’s ASC 842 accounting software helps teams maintain schedules, journal entries, and disclosures. For a closer look, book a demo using a lease from your own portfolio.
Is a capital lease the same as a finance lease?
Capital lease was the term ASC 840 used for a similar type of lease. ASC 842 changed the name to finance lease and revised the tests. The name and the rules both depend on the standard you use.
Some older contracts and policies still use the term capital lease. Canadian private firms using ASPE 3065 still use it as well.
| Term | Where it applies | What the label describes |
|---|---|---|
| Capital lease | Legacy ASC 840; current ASPE 3065 | A lease with ownership-like accounting, assessed under the applicable standard |
| Finance lease | ASC 842 lessees; IFRS 16 lessors | A classification whose criteria depend on the reporting framework |
| Operating lease | ASC 842; ASPE 3065; IFRS 16 lessors | A lease classified as operating under the relevant framework |
| True lease | Tax analysis | A tax classification assessed separately from financial reporting |
For the tax distinction, review how true leases differ from operating leases. The label in your accounts does not, by itself, decide the tax treatment.
What is a finance lease?
A finance lease meets at least one of ASC 842’s five classification tests. The lessee records a right-of-use asset and a lease liability. It records interest on the lease balance and ROU amortization as two costs.
If the contract transfers ownership, the lease meets one of those tests. Other terms, such as using the asset for most of its remaining life, can also meet a test.
What is an operating lease?
An operating lease meets none of ASC 842’s five finance lease tests. The lessee usually records a right-of-use asset and a lease liability. It spreads one lease cost across the term, usually on a straight-line basis.
An office, vehicle, or equipment lease can meet these operating lease rules. Check the lease terms before deciding how to record any of these assets.
Lessees can elect to leave eligible short-term leases off the balance sheet. The lease term must be 12 months or less at commencement. The lease must exclude purchase options that the lessee is reasonably certain to exercise. Calling a lease operating does not, by itself, keep it off the balance sheet.
Finance lease vs operating lease: side-by-side comparison
The table covers leases where the lessee records both an ROU asset and a liability. It assumes no impairment or unusual terms that change the expense pattern.
| Topic | Finance lease | Operating lease |
|---|---|---|
| Classification | Meets at least one finance lease criterion | Meets none of the finance lease criteria |
| Balance sheet | ROU asset and lease liability | ROU asset and lease liability |
| Expense recognition | Separate interest and ROU asset amortization | Single lease expense, generally straight-line |
| Typical expense pattern | Higher total expense early in the term | Even expense over the term |
| Conventional EBITDA | Interest and amortization are added back | Single lease expense generally reduces EBITDA |
| Cash flow statement | Principal in financing activities; interest generally in operating activities | Lease payments generally in operating activities |
| Legal ownership | Can transfer, but transfer is not required | No ownership transfer under the assessed terms |
FASB’s lease accounting overview explains why both lease types usually appear on the balance sheet. The cost pattern and cash flow lines still depend on the lease type.
How do you classify a lease under ASC 842?
Test each separate lease component on the date the lease starts. If it meets any one test, the lessee records a finance lease. When it meets none, the lessee records an operating lease instead.
The tests below summarize ASC 842-10-25-2, including details that can change the result.
| Test | What to assess | Comparison with ASC 840 |
|---|---|---|
| Ownership transfer | Does ownership transfer to the lessee by the end of the term? | Ownership transfer also supported capital classification |
| Purchase option | Is the lessee reasonably certain to exercise an option to purchase the asset? | Replaces the bargain purchase option criterion |
| Economic life | Does the term cover a major part of the asset’s remaining economic life? | Replaces the mandatory 75% threshold with a principle |
| Fair value | Does the present value of payments and relevant lessee residual guarantees cover substantially all fair value? | Replaces the mandatory 90% threshold with a principle |
| Specialized asset | Will the asset have no alternative use to the lessor when the term ends? | Adds a separate criterion absent from ASC 840 |
Skip the economic-life test if commencement falls at or near the end of the asset’s economic life. The fair-value test also includes lessee residual guarantees not already in the lease payments.
A custom-built asset may still have another use when the lease ends. Check contract terms and practical limits on the lessor’s ability to sell or lease it again.
Do the 75% and 90% thresholds still apply?
ASC 842 does not require a fixed cutoff for either of these tests. FASB explains one reasonable way to apply them in its classification guidance.
That approach treats at least 75% of remaining economic life as a major part. It treats at least 90% of fair value as substantially all of that value. Record the basis you use and apply it the same way to similar leases.
Five-year example: identical payments under each classification
Assume two equipment leases have the same payments, timing, and discount rate. The facts differ, so one is a finance lease and the other is an operating lease. Those facts decide the lease type, rather than the expense pattern the lessee wants.
Neither lease transfers ownership or includes a purchase option reasonably certain of exercise. One meets the economic-life test; the other meets none of the finance lease tests.
| Assumption | Amount or treatment |
|---|---|
| Lease term | Five years |
| Annual payment | $100,000, paid at each year-end |
| Discount rate | 5% annually |
| Total cash payments | $500,000 |
| Opening lease liability | $432,947.67 |
| Opening ROU asset | $432,947.67 |
| Other payments and adjustments | No prepayments, incentives, initial direct costs, variable payments, modifications, or impairment |
Discounting each of the five annual payments gives the opening lease liability. For this example, we use a 5% incremental borrowing rate. Read the guide to choosing the borrowing rate for the factors behind that rate.
Expense recognition over the full term
The finance lease amortizes the ROU asset across the five-year term. Interest falls over time as each payment reduces the remaining lease balance. The operating lease records a single $100,000 expense each year.
| Year | Operating lease expense | Finance ROU amortization | Finance interest | Total finance expense |
|---|---|---|---|---|
| 1 | $100,000.00 | $86,589.53 | $21,647.38 | $108,236.91 |
| 2 | $100,000.00 | $86,589.53 | $17,729.75 | $104,319.28 |
| 3 | $100,000.00 | $86,589.53 | $13,616.24 | $100,205.77 |
| 4 | $100,000.00 | $86,589.53 | $9,297.05 | $95,886.58 |
| 5 | $100,000.00 | $86,589.55 | $4,761.91 | $91,351.46 |
| Total | $500,000.00 | $432,947.67 | $67,052.33 | $500,000.00 |
These illustrative calculations round annual amounts to the nearest cent. Final-year adjustments reconcile the liability and ROU asset to zero. Those adjustments add one cent to interest and two cents to amortization.
The finance lease records higher costs during the first three years. Its costs fall below the operating lease amount in year four. Both leases record $500,000 in total expense under these assumptions.
How the balance sheet changes after commencement
Both lease liabilities equal $354,595.05 after the first scheduled payment. At year-end, the finance ROU asset has fallen to $346,358.14. The operating ROU asset remains higher, at $354,595.05 after that payment.
To reduce the operating ROU asset, deduct interest accretion from the single lease expense. This preserves one reported lease cost, even though the balance calculation still uses interest. The asset balances can therefore differ after both leases start with the same amount.
Journal entries for the first year
At the start, each lessee debits its ROU asset for $432,947.67. Each lessee credits the lease liability for the same amount. These opening entries do not require either lessee to make a cash payment.
The numbers below show each model’s first-year costs and its cash payment. Keep separate accounts for each lease type when recording these entries.
| Scenario and entry | Debit | Credit |
|---|---|---|
| Finance: interest and payment | Interest expense $21,647.38; lease liability $78,352.62 | Cash $100,000.00 |
| Finance: ROU amortization | Amortization expense $86,589.53 | Accumulated ROU amortization $86,589.53 |
| Operating: single lease expense | Lease expense $100,000.00 | Lease liability $21,647.38; ROU asset $78,352.62 |
| Operating: annual payment | Lease liability $100,000.00 | Cash $100,000.00 |
Each entry balances, and both payment entries reduce cash by $100,000. The detailed guide to recording lease journal entries covers additional accounting scenarios.
Why does classification change EBITDA and cash flow presentation?
EBITDA starts with net income and adds back interest, taxes, depreciation, and amortization. The SEC’s EBITDA guidance sets out this definition and explains when to label a measure adjusted EBITDA.
To calculate EBITDA, add back finance lease interest and ROU asset amortization. The operating lease’s single cost normally still reduces that measure. In this example, finance treatment makes EBITDA $100,000 higher each year with all other results unchanged.
Both leases still have the same cash payments, regardless of how their accounting differs. ROU amortization can still reduce operating income in the financial statements. EBITDA adds that cost back; it does not change where it appears on the income statement.
The first finance payment includes $78,352.62 of principal and $21,647.38 of interest. Under the assumed US GAAP treatment, principal appears in financing cash flows. Interest appears in operating cash flows, while the operating lease’s entire payment appears there.
This matters when setting targets, valuing a business, or checking a loan covenant. Check how the company or lender defines EBITDA before using it to compare results. Black Owl’s guide covers lease effects on EBITDA and other financial ratios in more detail.
How does a lease affect financial ratios?
Recording a lease can add to both assets and liabilities from the start. How the ratios change depends on the formulas and loan terms you use.
Assume a company recognizes the finance lease from the example above. It starts with $2,000,000 in assets, $800,000 in liabilities, and $1,200,000 in equity. Current assets total $500,000, and current liabilities total $300,000 before commencement.
| Metric | Before commencement | After commencement |
|---|---|---|
| Total assets | $2,000,000.00 | $2,432,947.67 |
| Total liabilities | $800,000.00 | $1,232,947.67 |
| Equity | $1,200,000.00 | $1,200,000.00 |
| Current liabilities | $300,000.00 | $378,352.62 |
| Total liabilities divided by equity | 0.67 | 1.03 |
| Current ratio | 1.67 | 1.32 |
| Illustrative return on assets | 10.0% | 8.2% |
Using the principal-reduction approach, this example adds $78,352.62 to current liabilities. Future interest has not yet accrued, so that amount excludes it. In this example, equal opening asset and liability amounts leave equity unchanged.
To show the effect on ROA, assume net income stays at $200,000. Divide that figure by ending assets to show the effect of a larger asset base. Actual ROA often uses average assets, and lease costs can change net income as well.
The liabilities-to-equity ratio uses all liabilities, which may differ from the debt your lender counts. FASB discusses why operating lease liabilities may not count as debt. A loan may also use debt rules based on older accounting standards.
A higher ratio alone does not show that the business has breached a covenant. Review how lease liabilities affect loan covenants against the actual lending agreement.
What should a business review before signing?
Check which assets the business needs and the full amount it will have to pay. Allow for changes in those needs, as well as plans to replace the asset.
Leasing can spread cash payments across the years you use an asset. It may reduce the cash needed upfront, while leaving payments due in later years.
- Compare payment timing, purchase options, and expected use over the asset’s life.
- Check who pays for maintenance and insurance during the lease term. Also check return conditions and any charges for ending the lease.
- Use the lender’s terms when estimating the lease’s effect on loan covenants.
An operating lease still commits the business to payments and usually adds a lease liability. A finance lease does not, by itself, give the business ownership or tax benefits.
Common mistakes in lease classification
Treating operating leases as the default
A transfer of ownership meets one test, but four other tests also matter. Check all five tests before recording a lease as operating under ASC 842. The contract’s name and the type of asset do not settle the question.
Failing to document the initial assessment
Keep the contract, payment schedule, estimate of economic life, and support for fair value. Record the purchase options, residual guarantees, and conclusions about alternative use. These records show reviewers why your team reached its decision about the lease.
Missing a reassessment after the lease changes
A lease modification requires repeating the classification tests unless it qualifies as a separate contract. Also repeat the tests when the lease term or purchase-option assessment changes. A longer term may change the lease type, but check the tests before drawing that conclusion.
Use the same process for handling lease modifications and reassessments across your leases. Keep a record of the change date, new inputs, and journal entries.
Applying different policies across similar leases
Write down how your team applies major part and substantially all. Use those policies the same way across entities and similar leases. Review any exceptions before approving the schedules for the financial statements.
How do IFRS 16, GASB 87, and ASPE 3065 differ?
Each reporting standard has its own rules for how lessees account for leases. The ASC 842 split between finance and operating leases does not apply in all frameworks.
| Framework | Lessee model | Main recognition point |
|---|---|---|
| ASC 842 | Finance or operating classification | Both generally require an ROU asset and liability; eligible short-term exemptions apply |
| IFRS 16 | Single lessee model | ROU depreciation and liability interest, with short-term and low-value recognition exemptions |
| GASB 87 | Single financing model for covered leases | Lease asset and liability under accrual accounting, subject to scope and short-term exceptions |
| ASPE 3065 | Capital or operating classification | Capital leases create assets and obligations; operating leases generally produce rental expense |
The IFRS Foundation’s overview sets out the single lessee model and its exemptions. IFRS lessors still apply tests to classify leases as either finance or operating. Lessee accounting is similar to ASC 842 finance accounting, but the specific rules can differ.
GASB Statement 87 applies to leases of US state and local governments. Some leases are outside its model, such as short-term leases that meet its rules. GASB treats qualifying ownership-transfer contracts as financed purchases of the underlying asset. Governmental fund reports follow their own measurement focus and accounting basis.
Private Canadian firms using ASPE 3065 still classify leases as capital or operating. ASPE lessees usually record rent expense for their operating leases. They normally keep the leased asset and lease obligation off the balance sheet. Groups that use more than one standard need schedules that follow each set of rules.
How software supports finance and operating lease accounting
Black Owl Systems supports lessee and lessor accounting under ASC 842, IFRS 16, and ASPE 3065. Its lease records drive the schedules, journal entries, and disclosures the team uses at the close. Version history shows how lease changes shape the amounts in the books.
Your accounting team still reviews the lease terms and approves the lease type. That review covers renewal options, economic life, residual guarantees, and the lessor’s other uses for the asset. Software uses the approved inputs to keep calculations and reports consistent across the portfolio.
Review Black Owl’s features for lease accounting teams when comparing software against your close requirements. Look at how it handles lease changes, audits, disclosures, and reports across your companies.
Frequently asked questions
What is the difference between a finance lease and an operating lease?
Finance leases meet at least one of the five tests in ASC 842. Operating leases meet none and usually have one cost spread evenly across the term. Both types usually add a right-of-use asset and lease liability to the balance sheet.
Finance lease costs include interest and ROU amortization, which usually make total costs higher early. Cash flow lines and EBITDA also depend on which type applies.
Do both lease types appear on the balance sheet under ASC 842?
Finance and operating leases usually appear on the balance sheet under ASC 842. Lessees can elect an exemption for short-term leases that meet the rules. The lease liability equals the present value of lease payments still due.
The opening ROU asset calculation also includes prepayments, qualifying initial direct costs, and incentives. Those amounts can make the opening asset differ from the lease liability.
How do you classify a lease under ASC 842?
Lease classification under ASC 842 starts when the lessor makes the asset available for use. Check the five tests and record a finance lease if any one applies. They cover ownership transfer, purchase options, economic life, fair value, and alternative use.
Include relevant lessee residual guarantees in the fair-value test without counting them twice. If none of the tests applies, record the lease as operating under the ASC 842 rules.
Why does expense recognition differ between lease types?
Finance lease expense combines ROU asset amortization with interest on the unpaid lease balance. The interest charge usually falls as the lessee pays that balance down. That makes total finance lease costs higher in the early years of the term.
Operating leases usually spread one lease cost evenly over the same period. The example’s total costs match, but impairment, terms, or longer amortization periods can change that result.
Does the same classification apply under IFRS 16?
IFRS 16 uses one main lessee model, with separate ROU depreciation and interest on the lease liability. Short-term leases and leases of low-value assets can qualify for recognition exemptions. Lessors still use the finance and operating classifications under the IFRS 16 rules.
The guide to reporting under IFRS 16 and ASC 842 explains what the two sets of rules require. Check each standard before using one schedule for both sets of financial statements.
Is a capital lease the same as a finance lease?
Capital lease was ASC 840’s name for a similar type of lease. ASC 842 changed that name to finance lease and also revised the tests. The old name alone does not prove which accounting rules apply to today’s contract.
Canadian private firms that follow ASPE lease accounting requirements still use the capital lease label. Check which standard applies before using rules written for a different one.
What is the 90% rule in lease classification?
The 90% rule was a mandatory test under the old ASC 840 standard. ASC 842 instead uses substantially all when comparing present value to fair value. FASB accepts 90% as one reasonable way to apply that test.
Your policy should state which approach you use and why it fits your leases. Include relevant lessee residual guarantees and apply the chosen approach the same way each time.
Can a lease change classification after commencement?
Lease classification can change when the contract changes or other rules require a new assessment. A lease modification requires repeating the tests unless you account for it as a separate contract. Also retest when the lease term or your assessment of a purchase option changes.
An index-linked payment increase alone does not trigger ASC 842 liability remeasurement. Check what changed before deciding which amounts and accounting treatments to update in your records.
Manage finance and operating leases in one system
The correct lease type sets the basis for how your team records the lease. Keep that decision clear as the lease changes and each reporting date arrives.
- Keep schedules for both operating and finance leases in one system.
- Use the same lease records to generate journal entries and disclosures.
- Keep past versions of each lease to track changes and support reported balances.
Review Black Owl’s pricing options or schedule a portfolio walkthrough to work through your leases with the team.

Greg Kautz
Greg Kautz, CPA, CMA is a seasoned management consultant and professional accountant with over 40 years of experience in the consulting and energy sectors. At Black Owl Systems, Greg brings deep expertise in ERP systems, corporate finance, strategic planning, and technology integration.
